Retirement planning is about more than reaching a specific savings number. It is about creating a financial structure that supports the lifestyle, goals, and priorities individuals want to pursue after leaving the workforce.
Many financial decisions made before retirement influence future opportunities. Savings, investments, taxes, healthcare planning, and income strategies all play a role in determining how prepared someone may be for retirement.
Financial planning for retirement focuses on connecting financial resources with personal objectives. It considers not only how much wealth has been built but also how those assets can support a meaningful retirement.
A life-centered financial approach helps individuals create a plan that balances financial security with personal priorities.
Quick Answer
Financial planning for retirement is the process of organizing savings, investments, income sources, and financial decisions to support life after work.
A complete retirement wealth planning strategy may include:
- Defining retirement goals
- Estimating future expenses
- Building retirement savings
- Managing investments
- Creating income strategies
- Planning for healthcare costs
- Considering taxes
- Reviewing estate goals
The goal is creating a financial framework that supports both retirement security and personal priorities.
Why Should Retirement Planning Focus on Life Goals?
Retirement is not only a financial milestone. It is a major lifestyle transition.
After leaving the workforce, individuals may want to:
- Spend more time with family
- Travel
- Pursue hobbies
- Support loved ones
- Volunteer
- Explore new interests
A retirement plan should consider what individuals want their retirement years to look like.
Financial decisions are most effective when they support meaningful personal goals.
What Is Life-Centered Financial Planning?
Life-centered financial planning focuses on connecting money decisions with personal priorities.
Instead of asking only:
“How much money is needed for retirement?”
A broader approach also considers:
- What lifestyle does retirement support?
- What experiences are important?
- What responsibilities need to be planned for?
- What legacy goals matter?
This approach creates a more complete view of retirement preparation.
Building a Strong Retirement Foundation
A successful retirement strategy begins with understanding the current financial situation.
Important areas include:
- Current savings
- Investments
- Income sources
- Expenses
- Financial obligations
- Future goals
This information helps create a realistic retirement roadmap.
Defining Retirement Goals
The first step in retirement preparation is identifying personal objectives.
Goals may include:
Lifestyle Goals
Examples:
- Maintaining a preferred standard of living
- Traveling
- Supporting personal interests
Family Goals
Examples:
- Helping family members
- Supporting future generations
Legacy Goals
Examples:
- Transferring wealth
- Supporting charitable causes
Clear goals provide direction for financial decisions.
Estimating Retirement Expenses
Understanding future expenses is essential for retirement planning.
Expenses may include:
Essential Expenses
Such as:
- Housing
- Utilities
- Food
- Insurance
- Healthcare
Lifestyle Expenses
Such as:
- Travel
- Recreation
- Entertainment
- Personal interests
Future Expenses
Such as:
- Long-term care
- Home adjustments
- Unexpected needs
A realistic estimate helps determine future income requirements.
Creating Retirement Income Strategies
During working years, income often comes from employment.
During retirement, income may come from:
- Retirement accounts
- Investment portfolios
- Social Security benefits
- Pension income
- Other assets
A retirement income strategy helps organize how these resources may support expenses.
Why Is Retirement Income Planning Important?
Having retirement savings does not automatically create a sustainable income plan.
Important considerations include:
- How much to withdraw
- Which accounts to use
- How investments should be managed
- How taxes affect withdrawals
A structured approach helps individuals make informed decisions about using retirement assets.
Managing Investments During Retirement
Investments continue to play an important role after retirement.
A retirement investment strategy may consider:
- Growth needs
- Income requirements
- Risk management
- Inflation protection
The appropriate approach depends on personal goals, timeline, and financial circumstances.
The Importance of Diversification
Diversification helps spread investments across different asset categories.
A diversified portfolio may include:
- Stocks
- Bonds
- Cash
- Real estate investments
- Other assets
The SEC explains that diversification may help reduce investment risk by spreading investments across different assets, although it cannot eliminate losses entirely.
For retirees, diversification can be an important part of managing long-term uncertainty.
Planning for Healthcare Costs
Healthcare is one of the most important retirement considerations.
Potential expenses may include:
- Insurance premiums
- Medical services
- Prescription costs
- Long-term care
Including healthcare planning in retirement strategies helps create more realistic financial expectations.
Considering Taxes in Retirement Planning
Taxes can influence retirement decisions.
Important considerations may include:
- Retirement account withdrawals
- Investment income
- Required distributions
- Estate transfers
A tax-aware retirement approach considers how different financial decisions may affect long-term outcomes.
Protecting Retirement Wealth
Retirement planning is not only about growth. Protecting assets is also important.
Wealth protection strategies may include:
- Insurance planning
- Emergency reserves
- Investment diversification
- Estate planning
These strategies help prepare for unexpected financial challenges.
Estate Planning and Legacy Goals
Many individuals want their wealth to support others after retirement.
Estate planning may involve:
- Beneficiary designations
- Wills
- Trusts
- Charitable giving
- Family goals
A clear legacy strategy helps organize future wealth transfer.
Why Should Retirement Plans Be Reviewed Regularly?
Financial circumstances change over time.
Retirement plans may need updates because of:
- Market conditions
- Family changes
- Healthcare needs
- Lifestyle changes
- New financial priorities
Regular reviews help keep strategies aligned with current goals.
Retirement Wealth Planning Framework
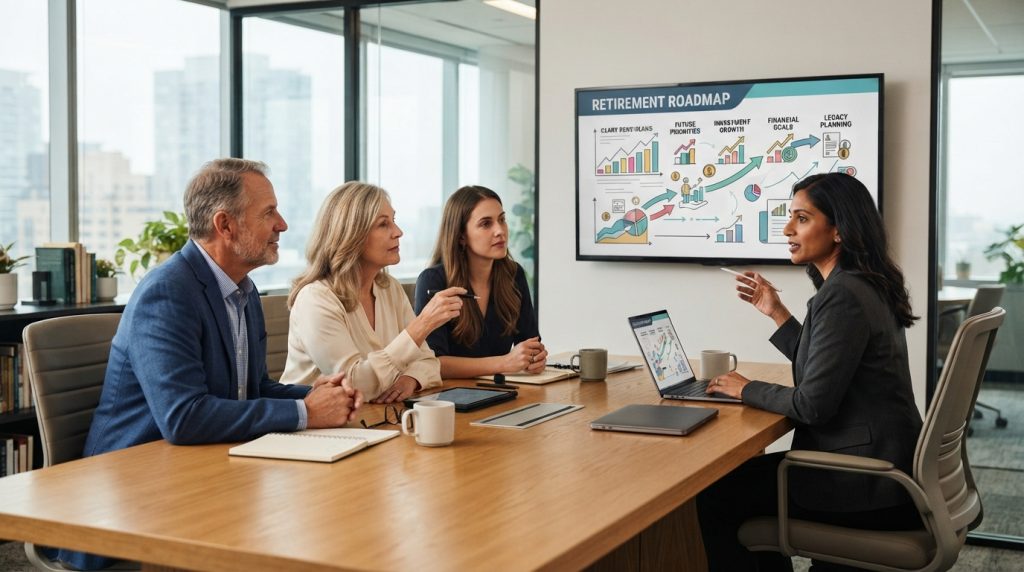
Step 1: Understand Current Financial Position
Review:
- Assets
- Investments
- Income sources
- Expenses
- Liabilities
Step 2: Define Retirement Vision
Identify:
- Desired lifestyle
- Personal priorities
- Retirement timeline
Step 3: Estimate Future Needs
Evaluate:
- Retirement expenses
- Healthcare costs
- Inflation impact
Step 4: Build Income Strategy
Consider:
- Retirement accounts
- Investment income
- Withdrawal planning
Step 5: Protect Financial Resources
Review:
- Insurance needs
- Risk management
- Estate planning
Step 6: Monitor and Adjust
Update the strategy based on:
- Life changes
- Financial circumstances
- Retirement goals
Retirement Planning Checklist
Goals
- Define retirement lifestyle goals.
- Establish retirement timeline.
- Identify personal priorities.
Savings
- Review retirement savings.
- Evaluate progress toward goals.
- Consider future income needs.
Investments
- Review portfolio strategy.
- Maintain diversification.
- Evaluate risk levels.
Income
- Identify retirement income sources.
- Plan withdrawal strategies.
- Consider tax implications.
Protection
- Review healthcare planning.
- Maintain emergency resources.
- Update estate documents.
Common Retirement Planning Mistakes
Focusing Only on Savings
Retirement success depends on how assets are managed, not only how much has been accumulated.
Ignoring Lifestyle Goals
A financial plan should support the life individuals want to experience.
Underestimating Healthcare Costs
Healthcare expenses can significantly affect retirement resources.
Delaying Retirement Planning
Early preparation provides more flexibility.
Failing to Update Plans
Financial circumstances and personal goals change over time.
Frequently Asked Questions
What is financial planning for retirement?
Financial planning for retirement is the process of organizing savings, investments, income sources, and financial decisions to support future retirement goals.
Why should retirement planning include personal goals?
Retirement is a lifestyle transition. Including personal goals helps create a financial strategy designed around the life individuals want to pursue.
How does retirement wealth planning work?
Retirement wealth planning combines savings, investments, income strategies, risk management, and future goals into a coordinated approach.
When should retirement planning begin?
Retirement planning can begin at any stage. Starting earlier may provide more time to save and adjust strategies, but planning remains valuable throughout life.
Why is investment planning important during retirement?
Investment planning helps manage retirement assets while considering income needs, risk, inflation, and long-term financial goals.
Final Thoughts
Retirement planning is about creating financial support for the next stage of life.
A strong retirement strategy considers:
- Personal goals
- Savings
- Investments
- Income planning
- Healthcare
- Wealth protection
- Legacy objectives
A thoughtful retirement wealth planning approach helps individuals connect financial decisions with the lifestyle they want to achieve.
Retirement is not a single event. It is an ongoing journey that requires preparation, flexibility, and regular evaluation.
By creating a life-centered financial plan, individuals can build a stronger foundation for managing wealth and pursuing meaningful retirement goals.
This article is intended for general educational purposes only. It does not provide individualized investment, tax, legal, accounting, insurance, retirement, estate planning, or financial advice. Individuals should consult qualified professionals regarding their specific circumstances.